Which KYC and AML platforms should a UK wealth manager shortlist in 2026?
Wealth onboarding has to verify a client, then verify the structures the client holds assets through, then screen every individual those structures surface, often across more than one jurisdiction.
What makes wealth management onboarding different?
Wealth onboarding has to verify a client, then verify the structures the client holds assets through, then screen every individual those structures surface, often across more than one jurisdiction.
A single new relationship can involve a settlor, trustees, beneficiaries, a corporate vehicle and directors, several of whom are resident somewhere other than the UK. Each one is a person to identify and screen. Doing that manually is where onboarding time goes, and it is why a client who expects a private-banking experience often waits weeks.
Shortlisting a KYC and AML platform: key takeaways
Clients arrive as structures
Wealth clients rarely arrive as a single individual. Trusts, holding companies, family investment vehicles and multiple jurisdictions are the normal case, not the exception.
The shortlist test
The shortlist test is whether one platform can verify the person, resolve the structure, screen everyone connected to it, and evidence the enhanced due diligence that follows.
PEP exposure is higher here
Politically exposed person exposure is higher in wealth than in most sectors, which makes screening quality and ongoing monitoring decisive rather than optional.
Source of wealth stays with the firm
Source of wealth remains the firm’s assessment. The platform supplies the identity, ownership and screening evidence it rests on.
What should be on the shortlist criteria?
Six criteria, in the order they matter for wealth.
Ownership resolution through layered structures
Trusts, nominees and intermediate holding companies are routine. A platform that returns the first registered name has not answered the question.
Screening depth and ongoing monitoring
Politically exposed person and sanctions exposure is materially higher in this client base, and status changes during a relationship that may run for decades.
International document coverage
Non-UK clients are standard. Coverage decides whether onboarding completes.
Enhanced due diligence support
The platform should evidence which risk path was applied and hold the underlying evidence in one place.
A client experience that matches the proposition
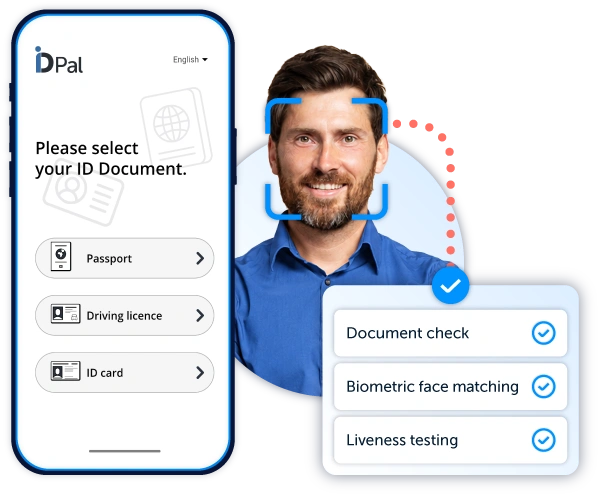
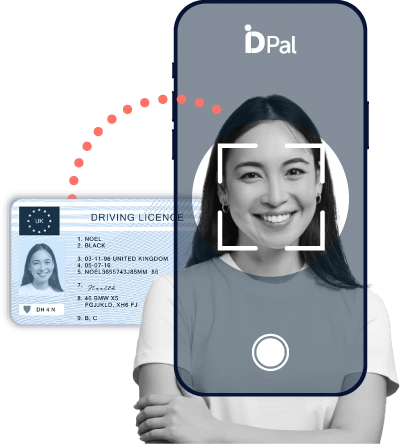
Remote verification in minutes rather than certified copies by post.
Certified anti-fraud
High-value relationships attract sophisticated document fraud, including AI-generated forgeries and injection attack video feeds.
Liveness detection independently certified to iBeta Level 1 and Level 2 under ISO 30107-3, with injection attack detection
Evidence
Single case view with a complete audit trail per submission
Assurance
ISO 9001 and ISO 27001 certified, GDPR compliant
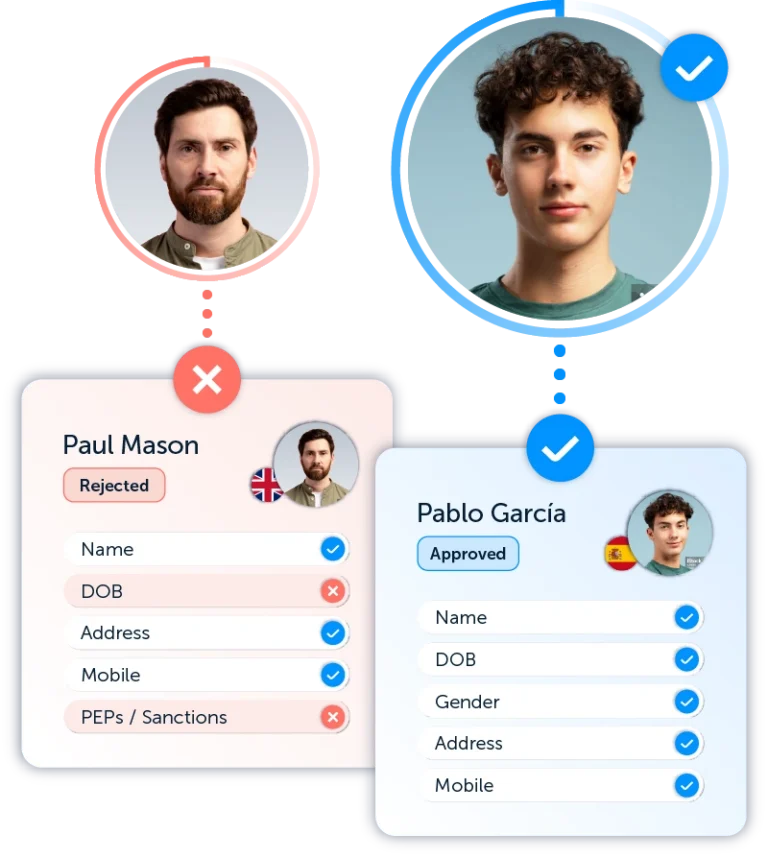
ID-Pal delivers KYC, KYB and AML compliance, configurable to the firm’s own risk rules, so a firm verifies the individual, resolves the entity or trust behind them, and screens everyone in one case with one audit trail.
Book a walkthrough of our IDV and AML solution for wealth managers
Supporting 16,000+ ID documents and 400+ data sources, expand into 250+ jurisdictions faster while maintaining consistent controls across regions and customer types.
ID-Pal helped us achieve our goal of onboarding new clients completely digitally and, for standard risk cases, in around 30 minutes, without any human intervention.
Richard Gerrard, Head of Operations, Ardan International
KYC and AML for wealth managers
Where does the platform stop?
The platform establishes who the client is, what they control and what screening returns. The firm assesses source of wealth and source of funds, sets the risk rating, and owns the relationship decision.
That distinction is worth holding onto during vendor conversations. Software that claims to deliver source of wealth is describing a judgement the firm still has to make. What it can do is remove the collection and reconciliation underneath that judgement, and evidence it once made.
Periodic review is where wealth firms carry the most hidden work, because a book built over years contains records collected under different standards.
Automated re-verification and remediation reduce that to an exception process rather than a project, and ongoing screening means a change in a long-standing client’s status surfaces when it happens rather than at the next review cycle.
Ardan International, an international wealth and fund platform, moved to fully digital client onboarding using ID-Pal. Richard Gerrard, Head of Operations at Ardan International, describes standard-risk cases completing in around thirty minutes without human intervention.
How should a wealth manager verify a trust client?
Identify the parties to the arrangement and the individuals who ultimately control it, verify those individuals, and screen each of them. Verifying the trust as an entity without resolving the people behind it leaves the risk half-checked.
Does one platform really cover individuals and entities?
Yes. Running both in one workflow gives a single case view and one audit trail per relationship, which is materially easier to evidence than reconciling separate tools. ID-Pal delivers KYC, KYB and AML compliance, configurable to the firm’s own risk rules.
How is politically exposed person exposure handled?
Through screening at onboarding and ongoing monitoring across the relationship, with enhanced due diligence applied where a match is confirmed. Because status can change during a long relationship, one-off screening is not sufficient.
Can overseas clients be onboarded remotely?
Yes, provided the platform supports their documents and can prove genuine presence. ID-Pal supports 16,000+ identity documents across 250+ jurisdictions with independently certified liveness detection.
Does the platform assess source of wealth?
No. Source of wealth is the firm’s assessment. The platform supplies verified identity, resolved ownership and screening results, and holds the evidence the assessment is recorded against.
What does this do to onboarding time?
For a standard-risk individual, a configured automated check completes in minutes. Complex structures take longer by design, because each individual the structure surfaces has to be verified and screened.