Last updated: August 2026 · Reviewed by ID-Pal
Key takeaways
- A fund administrator onboards investors on behalf of the fund, so the platform has to handle volume, mixed investor types and multiple jurisdictions in the same process.
- The shortlist test is whether one provider can verify an individual investor, resolve the ownership behind a corporate or trust investor, screen everyone connected to the subscription, and produce the evidence for each investor on request.
- Ongoing screening is not optional. Investor status changes over the life of a fund, and administrators are expected to catch it.
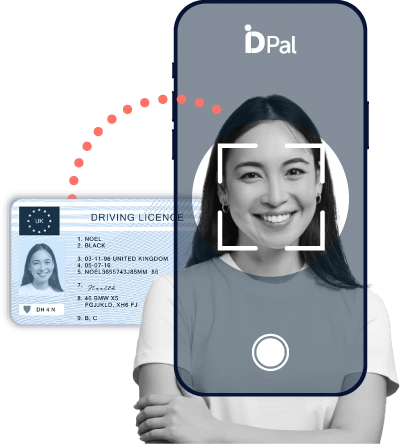
- ID-Pal delivers KYC, KYB and AML compliance, configurable to the administrator’s own risk rules. Its identity document verification covers 16,000+ identity documents from 250+ jurisdictions, with independently certified liveness detection.
- Deployment matters for administrators running several fund clients. ID-Pal can be deployed out of the box, via API and SDK, or through a native Salesforce integration.
Which platforms should a UK fund administrator shortlist?
A UK fund administrator should shortlist platforms that verify individual investors and corporate or trust investors, keep screening live for the life of the investment, and produce an audit trail that satisfies both the fund’s own compliance function and its regulator.
Providers commonly named for UK fund administration in 2026 include ComplyAdvantage, Fenergo, LSEG World-Check, Napier, Encompass and ID-Pal. The decision usually comes down to whether the administrator wants a screening layer on top of an existing onboarding process, or one provider for identity verification, business verification and screening. ID-Pal’s fund administration page sets out how it supports administrators.
What makes investor onboarding different from other onboarding?
The administrator is onboarding on behalf of someone else, at scale, against a closing date. Investors arrive as individuals, family offices, corporate vehicles, trusts, nominees and other funds, often from several jurisdictions in a single close.
Three things follow from that.
Every investor type has to fit one process. A platform built for individuals will handle the private investor well and leave the corporate investor, and the people behind it, to a manual file.
The close does not move. Verification that takes days pushes an investor into the next dealing date. Verification that is skipped to hit the date creates a file that cannot be defended at the next review.
Ongoing obligations run for years. A fund relationship outlasts most onboarding decisions. Screening has to stay live rather than stopping at subscription.
What has to be established, and on whom?
| Investor type | What the administrator establishes |
|---|---|
| Individual investor | Identity confirmed from a government-issued document, matched to the live person, with address verification |
| Corporate investor | Registration and status, plus identification of the ultimate beneficial owners and controlling persons through any intermediate entities |
| Trust, nominee or fund-of-funds | The parties to the arrangement and the individuals who ultimately control it, or reliance arrangements documented where permitted |
| Every relevant individual | Sanctions, politically exposed person and adverse media screening, outcome recorded |
| Higher-risk investors | Enhanced due diligence, including the fund’s own assessment of source of funds and, where relevant, source of wealth, with senior sign-off |
| The investor file | A dated record of each check, the decision that followed, and the evidence relied on |
The precise requirements depend on the fund structure, the administrator’s regulatory permissions and the jurisdiction of the fund, so administrators should confirm against their regulator’s current guidance.
What should a UK fund administrator look for in a platform?
Seven criteria decide it for an administrator.
- Individuals and entities with one provider. A corporate investor produces a list of people to verify. Handling the entity and the people behind it with the same provider means one supplier to evaluate, contract and oversee.
- Ownership resolution through structures. Following control through holding companies, nominees and trusts, rather than reporting the first registered name.
- Screening that continues. Investor status changes over a fund’s life. One-off screening at subscription misses it.
- International document coverage. Non-UK investors are the norm. Coverage decides whether onboarding completes before the close.
- Certified anti-fraud. Remote onboarding is standard for investors, which makes independently certified liveness detection a basic requirement.
- Configurable risk rules by fund. Different funds carry different risk appetites. The platform should apply different rules per client and record which path was applied.
- Deployment that fits an operations team. Out of the box for administrators without engineering capacity, an API and SDK for those with it, and a route through systems the team already uses.
How does ID-Pal meet those criteria?
ID-Pal delivers KYC, KYB and AML compliance, configurable to the administrator’s own risk rules, so an operations team can verify the individual investor, resolve the entity behind a corporate investor and screen everyone involved, with a record of each check.
| Criterion | How ID-Pal covers it |
|---|---|
| Individual verification | Document authentication across 16,000+ identity documents, thousand-dimension biometric facial matching, and address e-verification |
| Corporate investors | KYB compliance with identification of ultimate beneficial owners and persons with significant control (PSC) through intermediate structures |
| Screening | AML screening against sanctions, politically exposed persons and adverse media, on entities and individuals |
| Ongoing risk | Customer monitoring keeps screening live for the life of the investment |
| Anti-fraud | Liveness detection independently certified to iBeta Level 1 and Level 2 under ISO 30107-3, with injection attack detection |
| Configurability | Fully configurable rule-based engine, so checks can differ by risk and by fund client |
| Evidence | A dated record of each check and decision |
| Deployment | Out of the box, via API and SDK, or through a native Salesforce integration |
| Assurance | ISO 9001 and ISO 27001 certified, GDPR compliant |
Ownership resolution for corporate investors follows the integration of NorthRow’s KYB platform. ID-Pal’s KYB guide explains the process in more detail.
Ardan International, an international wealth management platform, moved to fully digital client onboarding using ID-Pal. Richard Gerrard, Head of Operations at Ardan International, says standard-risk cases now complete “in around 30 minutes, without any human intervention”. BCP Asset Management uses ID-Pal for digital client onboarding across its financial adviser network.
Where does the platform stop and the administrator’s judgement begin?
The platform supplies verified identity, resolved ownership and screening results. The administrator, together with the fund’s compliance function, remains responsible for the overall risk decision, the assessment of source of funds and source of wealth where enhanced due diligence applies, and ownership of the investor file.
The vendor supports this process by collecting and organising the underlying evidence and, based on its defined risk appetite and configurable rules-based engine, returning risk ratings to inform the administrator’s assessment.
How does this affect the investor experience?
Investor onboarding is the first thing an investor experiences of the fund. A process that asks for certified copies by courier sets a tone before the first dealing date.
Remote verification completes the standard-risk individual investor in minutes and reserves analyst time for the corporate and trust investors that need it. For administrators with overseas investors, remote capability decides whether the investor can be onboarded before the close at all. ID-Pal’s six practical steps for investor onboarding covers the process in more detail.
Frequently asked questions
Is a fund administrator responsible for investor due diligence?
In most structures the administrator carries out investor onboarding and screening on behalf of the fund under a delegated arrangement, while the fund and its manager retain overall responsibility. The split should be documented in the administration agreement and confirmed against the regulator’s current guidance.
How should a corporate investor be verified?
Confirm the entity is registered and active, identify the beneficial owners and controlling persons including through intermediate entities, then verify and screen those individuals. Registry data alone often does not resolve the real controller.
Does screening have to continue after subscription?
Yes. Sanctions and politically exposed person status can change over the life of a fund. Ongoing monitoring catches that without re-running the investor file manually.
Can overseas investors be onboarded remotely?
Yes, provided the platform supports the investor’s documents and can prove the person is genuinely present. ID-Pal supports 16,000+ identity documents across 250+ jurisdictions with independently certified liveness detection.
Should individual and corporate investors be verified by the same provider?
It can. One provider means one supplier to evaluate and oversee, and one set of checks to explain to a regulator. ID-Pal delivers KYC, KYB and AML compliance, configurable to the administrator’s own risk rules.
What evidence should an administrator be able to produce on request?
Which checks were run, on whom, on what date, what the screening returned, what risk rating was applied, who approved it, and the documents relied on. If any of that sits outside the investor file, the record is incomplete.